
Credit Cards, made simple
From your first card to chasing miles and cashback — plus everything you need to know about the credit score that decides your approval and limit.
Featured Guide
Latest on Credit Cards
Best No Annual Fee for Life (NAFFL) Credit Cards in the Philippines (Oct 2026)
Eight cards compared by income requirements, rewards and the catches — including Maya Black's monthly-use condition.
Best Beginner Credit Cards in the Philippines (Oct 2026)
Compare starter cards with low income requirements, no annual fee options, and tips for first-time applicants.
Best Travel Credit Cards in the Philippines (Oct 2026)
Miles, lounge access, FX fees, and annual fee waivers — our deep-dive comparison of the top travel cards for Filipinos.
Best Cashback Credit Cards in the Philippines (Oct 2026)
Top rebate rates on dining, groceries, fuel, and everyday spend — compared with real net cashback numbers.
Balance Transfer Philippines: 2026 Debt Playbook
Real cost vs add-on rate, bank fees, BSP rules, and when IDRP or a personal loan is the better move.
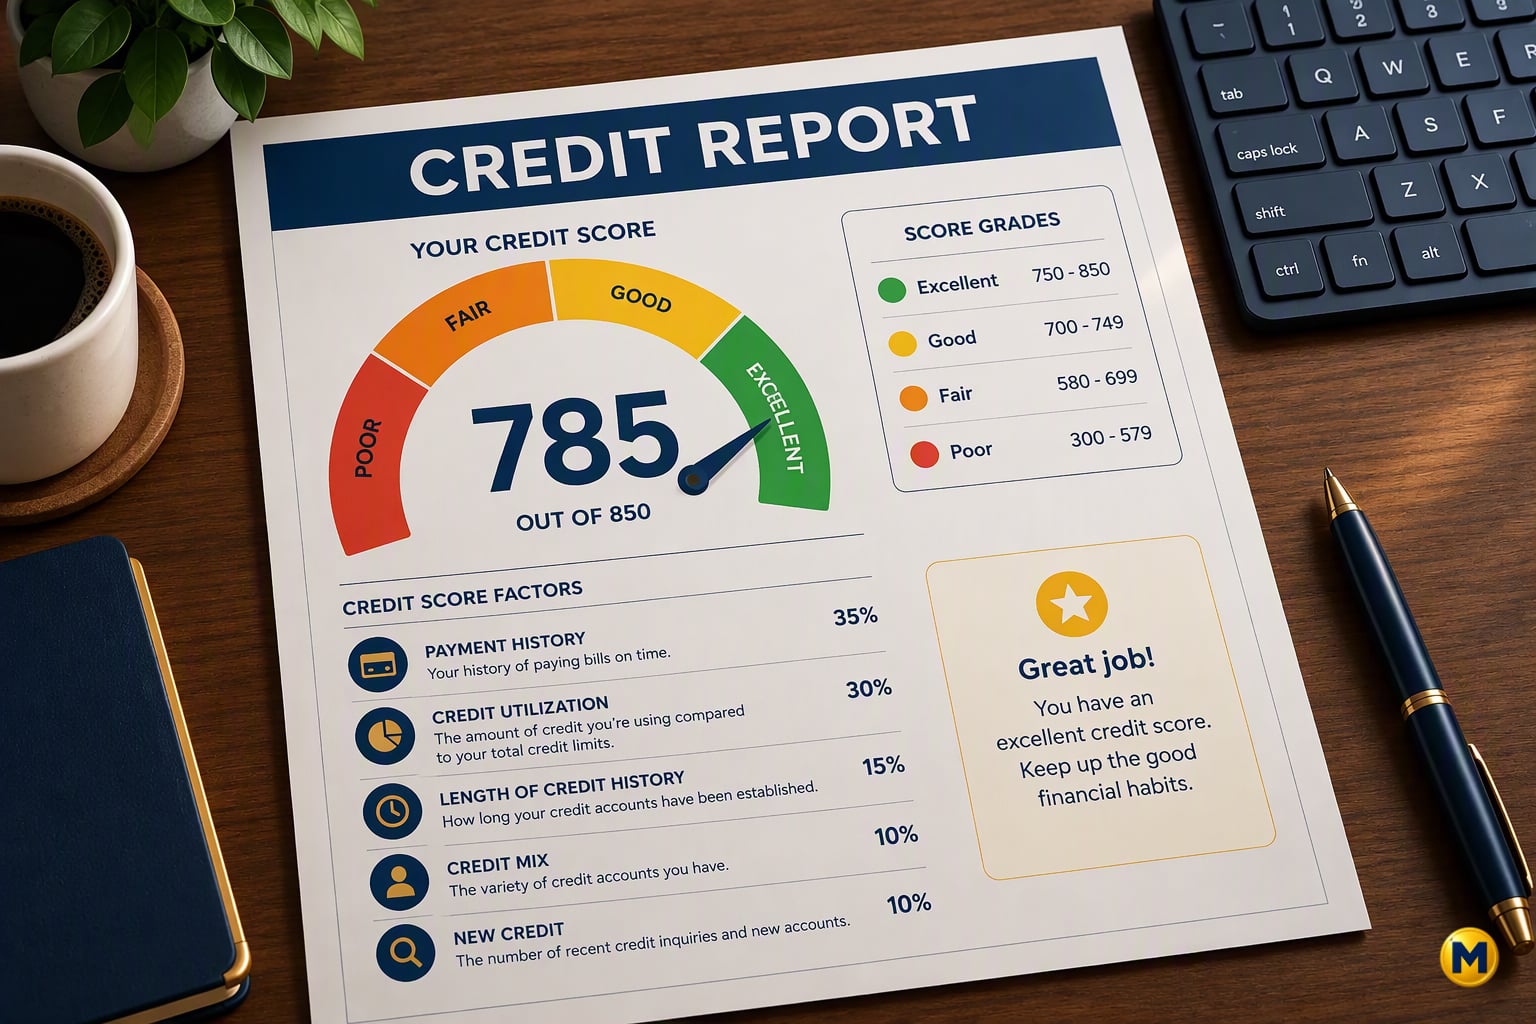
How to Check Your Credit Score in the Philippines (2026)
Pull your report from Lista PH, CIBI, or TransUnion — and push your score above 700.
Credit cards in the Philippines, without the sales pitch
A credit card in the Philippines is only cheap if you clear the statement balance in full each month. Interest is capped by BSP regulation but is still high relative to any rewards rate, so a card that earns cashback while carrying a revolving balance loses money on net. The first question is therefore not which card earns most, but whether you will pay in full.
For people who do, the comparison comes down to the effective rebate rate on the categories you actually spend in, annual fee waiver conditions, foreign-transaction charges, and the value of any bundled travel or lounge benefits. Rewards points are worth comparing in pesos per point, not in points earned.
Our guides cover beginner and first cards with easier approval, cashback cards, and travel cards, with the fine print that determines real value: earning caps, excluded merchant categories, minimum spend for waivers, and how installment conversions affect rewards.
- Pay the full statement balance, not the minimum — minimum payments extend the balance for years.
- Compare rebates in pesos per ₱1,000 spent in your own top categories.
- Foreign-currency purchases usually carry an assessment plus issuer charge on top of the FX rate.
- Annual fee waivers are often conditional on spend or a phone request, not automatic.