
Best Travel Credit Cards in the Philippines (Oct 2026)
No single card wins for everyone — the right choice depends on how you spend and where you fly. Ranked by true peso-to-mile cost. Lower pesos per mile = better value.
Updated on Oct 9, 2026 · 8 min read
Fact Checked
Quick answer
The best travel credit card in the Philippines is the one whose miles, airline partners and travel benefits match how you actually spend and fly. Compare the true peso-per-mile cost after conversion, the foreign transaction fee, the annual fee, and which airport lounge visits are complimentary. A travel card only pays off if you use its benefits and settle the statement balance in full each month.
Key takeaways
- Compare pesos spent per airline mile, not just points earned — conversion ratios differ between cards.
- Bonus earning categories matter: a card that excels on overseas or airline spend may earn less on everyday purchases.
- Choose a card that transfers to the airline programme you actually use rather than spreading miles across several programmes.
- Lounge access is not always free; distinguish complimentary local access, annual free visits and paid international visits.
- Foreign transaction fees and annual fees reduce the value of your miles, while carrying a balance can wipe out the rewards.
Banks run credit card promos very frequently — so while that can mean faster approval, don't let a fast "yes" decide for you. Take a moment to make sure you're choosing the right card for your needs, not just the easiest one to get.
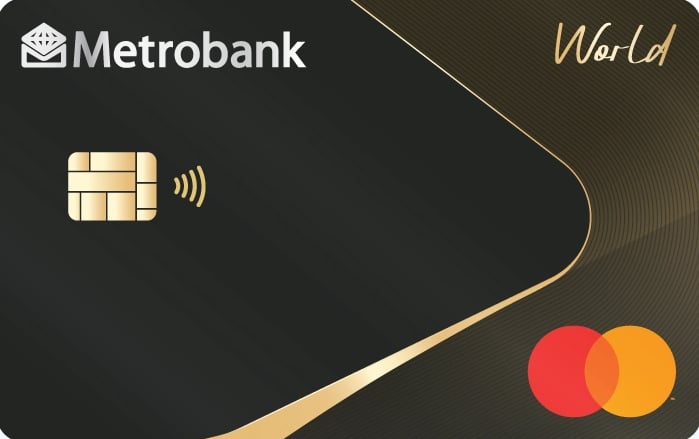
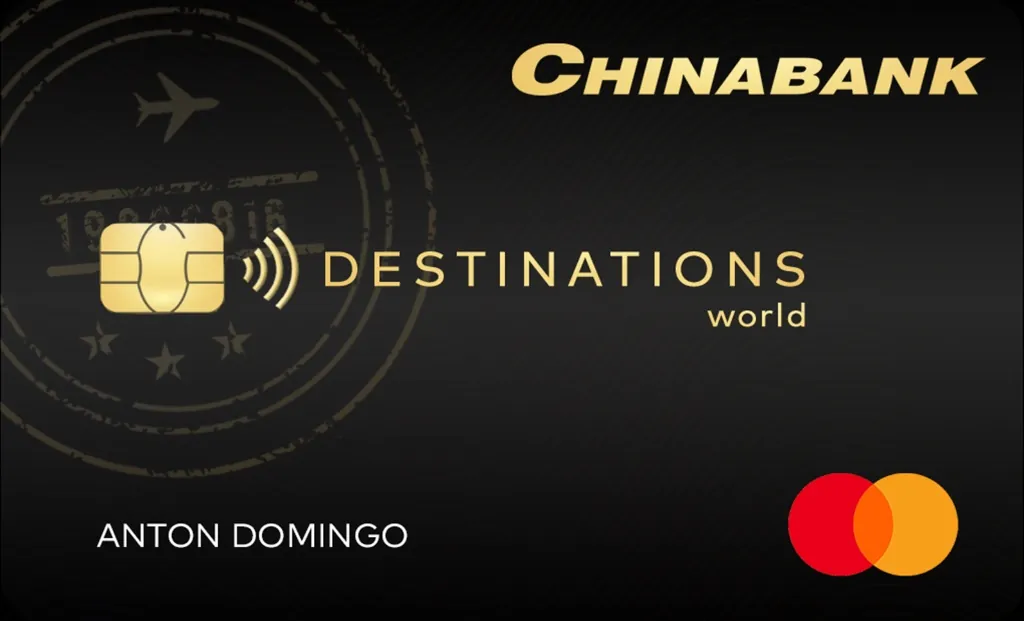
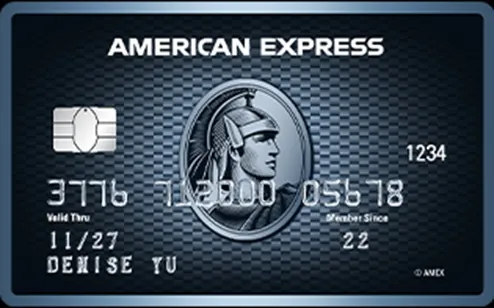
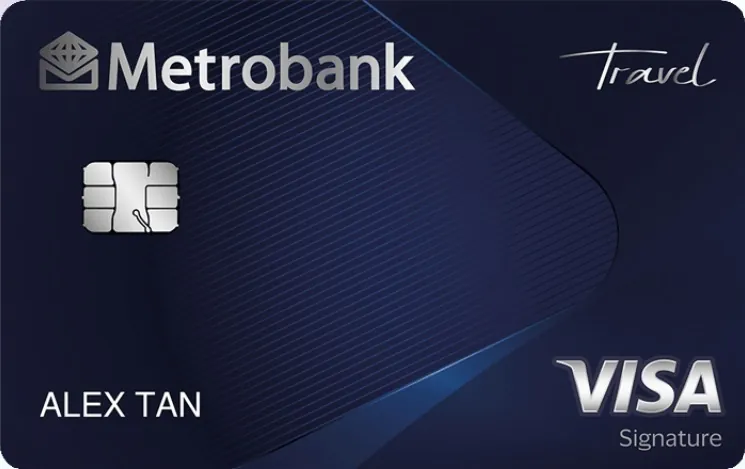
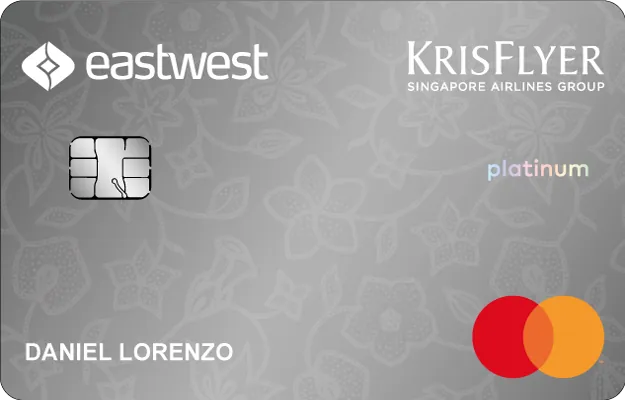
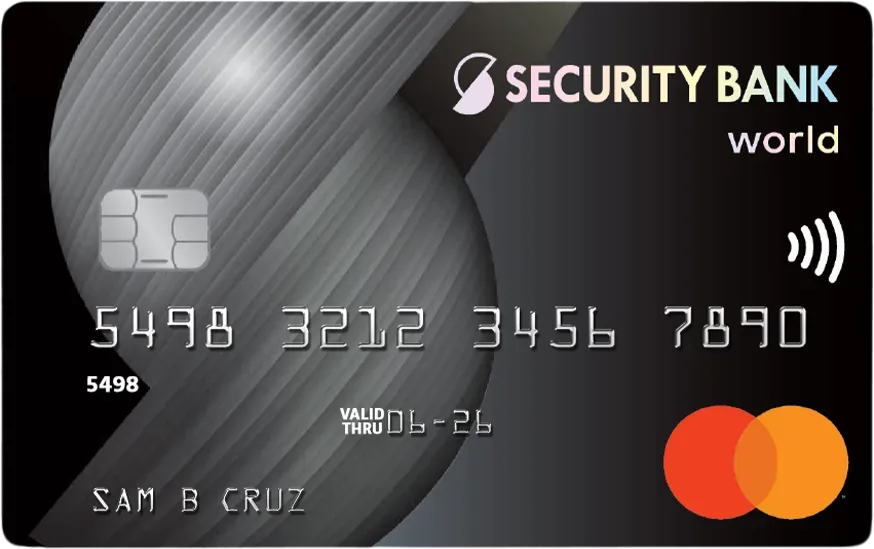
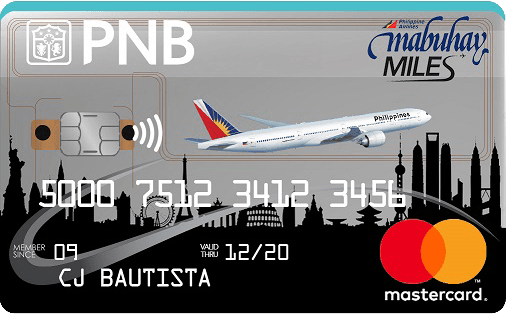
Travel credit card comparison table: miles, annual fees, FX fees and lounges
| Card | Earn rate (₱ per mile) | Annual fee | FX fee | Lounge access | Travel insurance |
|---|---|---|---|---|---|
| Metrobank World Mastercard | ₱17 intl / ₱50 local | ₱6,000 | 1.85% | Unlimited PAGSS + 2 free MTP | Included |
| Chinabank Destinations World MC | ₱30 all spend | ₱6,000 | 1.70% | DragonPass (paid) | ₱20M |
| BDO Amex Explorer | ₱30 all spend | ₱4,000 | 1.85% | Unlimited Marhaba | ₱10M |
| Metrobank Travel Signature Visa | ₱30 all spend | ₱5,500 | 1.68% | Unlimited local PAGSS + Plaza Premium; intl paid | ₱25M |
| EastWest KrisFlyer Platinum MC | ₱15 travel / ₱88 local | ₱4,000 | 1.70% | 4 free MTP visits | ₱20M |
| Security Bank World Mastercard | 3 pts / ₱20 | ₱5,000 (yr 1 free) | 2.50% | 1,300+ lounges, 6 free MTP | ₱10M |
| PNB PAL Mabuhay Miles World MC | ₱38 all / ₱30 PAL | ₱6,000 | 2.50% | World Assist concierge | Included |
Never accept an annual fee blindly. Most banks in the Philippines will waive this if you hit a specific yearly spend threshold. Even if you fall a bit short, call customer service — they often offer alternative milestones (like a quick 30-day spend challenge) to wipe the fee out.
Don't get blinded by complex, multi-tiered reward point systems or rotating bonus categories. Look for cards with clear, straightforward peso-to-mile ratios. The simpler the structure, the easier it is to track your progress and actually redeem your next free flight.
When swiping abroad or buying online in foreign currencies, high transaction fees can quietly wipe out your travel rewards. Standard cards charge up to 3.5% in markups. Prioritize cards offering low forex fees (around 1.68% to 1.85%) for all overseas spending.
Committing to a single airline carrier or alliance (like Star Alliance or Oneworld) pays off significantly faster. Focusing your miles and flights on one ecosystem unlocks premium perks — like lounge access, free baggage, and priority boarding — much quicker than spreading your spend across multiple airlines.
When a foreign merchant terminal or website asks if you want to be billed in Philippine Pesos (PHP) or local currency, always choose the local currency. Choosing PHP triggers Dynamic Currency Conversion (DCC), which locks in terrible, inflated exchange rates loaded with hidden margins.
You might be buying separate travel insurance unnecessarily. If you charge your entire international flight ticket to a premium travel credit card, it usually activates robust, complimentary travel accident and trip inconvenience coverage (for flight delays or lost luggage) automatically.
Keep an eye out for major annual events like the BPI or Metrobank Travel Fairs. Booking flights during these windows using the bank's co-branded or partner cards often unlocks exclusive discounts, massive bonus miles, or 0% interest installment plans you won't find anywhere else.
Never travel overseas relying on just one piece of plastic. Always bring a backup card on a different payment network (e.g., a Mastercard if your primary is a Visa) and store it separately. Unexpected fraud triggers or merchant terminal drops happen when you least expect them.
How we rank these cards
We convert every rewards programme into one number: the pesos you must spend to earn one airline mile. A card advertising "3 points per ₱20" tells you nothing until you know how many points convert into a mile — so we do that maths first, then weigh the annual fee, the foreign exchange markup, lounge access and travel insurance on top.
1. Work out your real earn rate
Cards on this list range from ₱17 to ₱88 per mile depending on where you swipe. If most of your spend is local groceries, fuel and utilities, a card like EastWest KrisFlyer (₱88/mile locally) will earn far slower than a flat ₱30/mile card — even though its travel rate looks better on paper.
2. Compare the annual fee against your yearly spend
At ₱30 per mile, a ₱6,000 annual fee is roughly 200 miles' worth of value you pay upfront each year. If you spend under about ₱30,000 a month, cashback usually beats miles — compare with our best cashback credit cards guide before you apply.
3. Do not ignore the FX markup
Foreign-currency purchases carry a markup of 1.68% to 2.50% on these cards, versus up to 3.5% on ordinary cards. On ₱200,000 of overseas spend, the gap between 1.68% and 2.50% is about ₱1,640 — often more than the miles you earned on that spend.
4. Never carry a balance on a miles card
Travel cards carry the same BSP-capped finance charges as any other credit card, and interest wipes out miles instantly. Run the numbers with our credit card interest calculator if you ever revolve a balance.
Travel credit card FAQs (Philippines, Oct 2026)
Which travel credit card in the Philippines gives the cheapest miles?
On our list, Metrobank World Mastercard is cheapest for international and travel spend at ₱17 per mile. For flat earning on everything, Chinabank Destinations World Mastercard, BDO Amex Explorer and Metrobank Travel Signature Visa all sit at ₱30 per mile.
What is the cheapest travel credit card annual fee?
BDO Amex Explorer (₱4,000) and EastWest KrisFlyer Platinum (₱4,000) have the lowest annual fees here. Most banks waive the fee once you hit an annual spend milestone — BDO Amex Explorer waives it at ₱450,000 a year.
Which card has the lowest foreign exchange (FX) fee?
Metrobank Travel Signature Visa charges 1.68%, followed by Chinabank Destinations and EastWest KrisFlyer at 1.70%. Standard non-travel cards in the Philippines can charge up to 3.5%, which quietly cancels out your miles.
Which travel credit card has unlimited airport lounge access?
Metrobank World Mastercard includes unlimited local PAGSS access plus 2 free Mastercard Travel Pass visits a year. Metrobank Travel Signature Visa includes unlimited access to participating local PAGSS and Plaza Premium lounges; international lounge visits via Visa Airport Companion (DragonPass) are paid separately. BDO Amex Explorer includes unlimited Marhaba lounges, and Security Bank World Mastercard covers 1,300+ lounges including PAGSS, Plaza and A lounges.
Is a travel credit card worth it if I only fly once a year?
Usually not. If you take one trip a year and spend under roughly ₱30,000 a month, a cashback card generally returns more value than paying a ₱4,000–₱6,000 annual fee for miles. See our cashback credit cards guide to compare.
How many miles do I need for a free domestic flight?
Award pricing changes by airline, route and season, so check the airline's award chart before you commit. Use the peso-per-mile figures above to work out how much spend a given award will cost you in practice.
Disclaimer — Card features, earn rates, annual fees, partner airlines, and promotional offers are subject to change without notice. The information on this page is intended as a general guide only and may not reflect the most current terms. We recommend visiting each bank's official website or speaking with a representative before making any application decisions.
Read next
Best Cashback Credit Cards (Oct 2026)
If your spending is mostly local — groceries, dining, fuel — a cashback card often returns more than miles. See the top cashback picks.
Read the guide